How Does a Secured Credit Card Work?
Contents
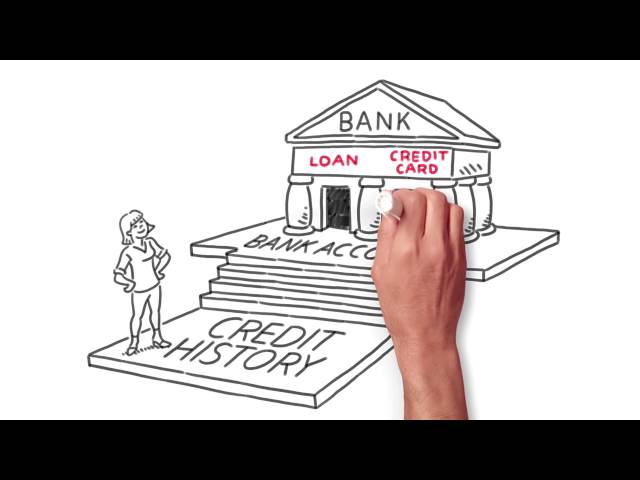
A secured credit card is a great way to build or rebuild your credit. But how does a secured credit card work? We break it down for you.
Checkout this video:
What is a secured credit card?
A secured credit card is a type of credit card that is backed by a deposit that you make with the issuer. The deposit serves as collateral for the credit card and is typically equal to your credit limit. This deposit gives the issuer protection in case you default on your payments.
With a secured credit card, you can build or rebuild your credit history by making timely payments. Secured cards are reported to the major credit bureaus, so if you use them responsibly, they can help improve your credit score over time.
Most secured cards require a minimum deposit, which will be your credit limit. Some issuers may require a higher deposit if you have poor credit or no credit history. You may also be charged an annual fee, and some issuers may charge additional fees for things like balance transfers and cash advances.
Before you apply for a secured card, make sure you understand the terms and conditions so there are no surprises down the road. Once you’ve been approved and have made your deposit, you can start using your secured card just like any other credit card. Just remember to keep track of your spending and make your payments on time!
How does a secured credit card work?
A secured credit card is a great way to rebuild your credit. It works by you putting down a deposit, which is usually equal to your credit limit, and then you use the card like a regular credit card. The money you spend is deducted from your deposit, and as long as you make your payments on time, you’ll start to rebuild your credit.
How to qualify for a secured credit card
Most major issuers require a minimum security deposit, often $200 or more. To get the card, you must first send in your security deposit, which becomes your credit limit. In some cases, you may be able to make a partial payment or have a family member cosign with you to help qualify.
If you don’t have the cash on hand to cover a deposit, some issuers may let you finance your deposit over time. Once your account is open and you’ve been approved for credit, you can begin using your card like any other credit card—making purchases and paying your bill on time each month.
Over time, as you demonstrate responsible credit behavior by paying on time and keeping your balances low, you may be able to transition to an unsecured credit card.
How to use a secured credit card
A secured credit card is a type of credit card that requires you to deposit money into a savings account as collateral. The deposit serves as your credit limit, so the amount of money you have in the account will determine how much you can spend on your card. If you default on your payments, the issuer can dip into your deposit to cover their losses.
Most secured cards work like any other credit card, which means you’ll have to make monthly payments and pay interest on any balances that you carry. But because secured cards are designed for people with bad or no credit, they typically come with high interest rates and fees.
To get a secured card, you’ll need to open a savings account with the issuer and deposit at least the minimum amount required. Once your account is funded, you can start using your card just like any other credit card. Be sure to keep an eye on your balance and make timely payments, as this is one of the best ways to improve your credit score.
What are the benefits of a secured credit card?
A secured credit card is a type of credit card that is backed by a deposit that you make with the issuing bank. The deposit is typically equal to your credit limit, which means that if you deposit $500, you will have a $500 credit limit. This deposit acts as collateral for the issuer in case you default on your payments, and it also means that secured cards are less risky for issuers than unsecured cards. As a result, secured cards are often easier to get than unsecured cards, even if you have bad credit.
There are several benefits of secured cards for consumers. First, they can help you build or rebuild your credit history. Second, they can help you establish or improve your credit score. And third, they can provide you with a convenient way to make purchases and access cash.
If used wisely, secured cards can help you achieve all three of these goals. To make the most of your secured card, though, there are a few things to keep in mind. First, be sure to make all of your payments on time and in full. Second, use your card regularly but don’t max it out; aim for using no more than 30% of your credit limit each month. And third, don’t close the account once you’ve built up enough credit to qualify for an unsecured card; this will hurt your credit score instead of helping it.
What are the drawbacks of a secured credit card?
While secured credit cards can help you rebuild your credit, there are a few things to keep in mind before you apply. First, most secured cards have higher interest rates and annual fees than traditional credit cards. This means it’s important to pay your balance in full each month to avoid costly interest charges. Additionally, many secured cards require a deposit equal to your credit limit, which means you may have to tie up a large sum of money in an account that earns little or no interest. Finally, remember that your credit limit may be low compared to other cards, which can make it difficult to make major purchases or rent a car.
How to choose the best secured credit card for you
You might be considering a secured credit card if you have bad credit or no credit history. A secured credit card requires a security deposit, which acts as your credit limit. For example, if you deposit $500, your credit limit — and maximum balance — will be $500.
Your payment history is reported to the three major credit bureaus (Equifax, Experian and TransUnion), so using a secured card responsibly can help you build or improve your credit score.
To get started, compare offers from our partners to find the best secured credit card for you. Then, follow these steps:
1. Research the card issuer: Review the issuer’s website for information about fees, customer service and policies. Also, check out online customer reviews to see what others say about their experience with the issuer.
2. Determine your deposit amount: Most issuers require a deposit equal to your desired credit limit, but some may allow you to make a smaller initial deposit with the option to add more money later.
3. Apply for the card: Complete the online application or print and mail the paper application. You’ll need to provide personal information such as your name, address and Social Security number, as well as information about your income and employment status.
4. Wait for approval: Once your application is approved, the issuer will send you information about how to fund your security deposit. This is usually done with a check or money order.
5. Activate and start using your card: Once you receive your card in the mail, call the customer service number on the back of the card to activate it and start using it right away!